Start with a simple conversation. We aim to drive regional industry and innovation through collaborative research.
Working with a university may sound complicated, but the process is simple. Here is the flow from first consultation to putting results into practice.

What should I ask about?Anything — even a vague idea like "we want to solve this problem" is a perfect starting point.
Who should I contact?Our office. A URA (research administrator) will assist you.

What can you do?We help clarify your needs and introduce the most suitable researchers, proposing the best form of collaboration — academic consulting, joint research, or contract research.

What about contracts?From NDAs to joint research agreements, we coordinate and support the process.

Cost?Estimated individually based on the scope of research. Let us know your approximate budget.
Duration?From a few months to multi-year projects, flexibly designed around your goals.
Procedures?We will guide you individually according to your plan.

Tax incentives?Joint and contract research expenses with universities may qualify for tax credits under Japan's R&D tax incentive scheme (open innovation type). Please ask us for details.
Expenses for joint research or contract (commissioned) research with universities may qualify for Japan's R&D tax credit for "special experimental research expenses" — the so-called open innovation type. For joint or commissioned research with universities, 30% of qualifying expenses can be credited against corporate tax for the fiscal year (the rate is 20%, 25%, or 30% depending on the type of partner).
The credit is capped at 10% of corporate tax, separately from the general R&D tax credit. Requirements apply, including contract terms, expense accounting, and a confirmation procedure by the university (set out in METI's guideline).
Donations to national university corporations qualify as "designated donations" and, when used for statutory activities, are fully deductible for corporations. Individual donors are eligible for donation deductions.
The above is an outline only. Requirements such as contract terms and accounting apply — please consult us when requesting an estimate.
Search for researchers open to collaboration by keyword, industry, or department. (Interface in Japanese)
Search the databaseLook up faculty members by name, affiliation, or research keyword. (Japanese)
Find researchers
ShimaDAY, the university's official web media, introduces our researchers and their work. (Japanese)
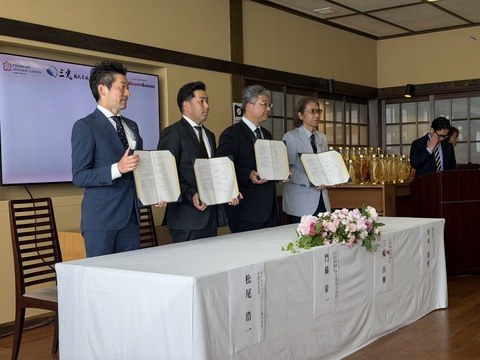
Read articlesRecent collaborations with companies and the local community. (Articles in Japanese)
We support your industry-academia-government collaboration and innovation. Feel free to reach out.
Open the contact form